The Malaysian Government announced proposed changes to individual income tax rates under Malaysia Budget 2027,
tabled on 9 October 2026. These adjustments aim to reduce the tax burden on certain middle-income taxpayers while strengthening the progressive taxation system for higher-income individuals.
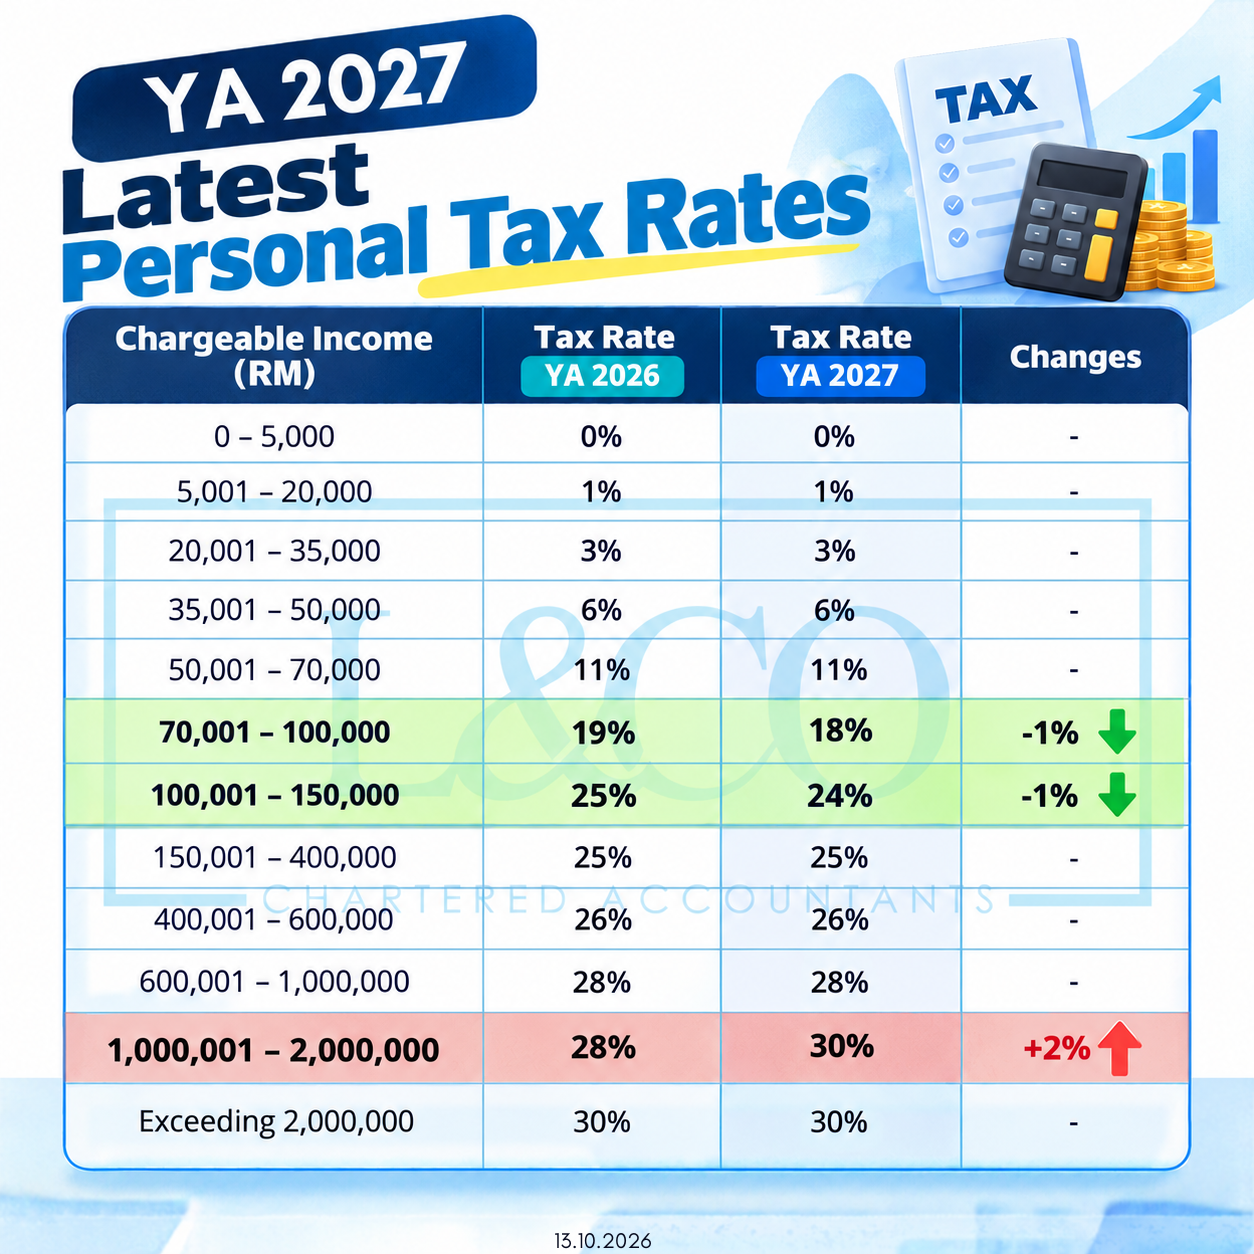
Under the proposals, selected personal income tax rates will be reduced by one percentage point,
while a higher tax rate will apply to the portion of chargeable income exceeding RM1 million.
1. Lower Income Tax Rates for Middle-Income Earners
One of the key highlights of Malaysia Budget 2027 is the reduction in personal income tax rates for selected middle-income brackets.
Chargeable Income from RM70,001 to RM100,000
The applicable tax rate is proposed to decrease from 19% to 18%, representing a reduction of one percentage point.
Chargeable Income from RM100,001 to RM150,000
The applicable tax rate is proposed to decrease from 25% to 24%, also representing a reduction of one percentage point.
These changes are intended to provide tax savings and increase disposable income for eligible taxpayers.
As Malaysia adopts a progressive taxation system, the lower rates apply only to the relevant portions of chargeable income rather than the taxpayer’s entire income.
2. Higher Income Tax Rate for High-Income Individuals
Malaysia Budget 2027 also proposes an adjustment to the personal income tax rate applicable to higher-income individuals.
Under the proposal, the tax rate for chargeable income between RM1,000,001 and RM2,000,000 will increase from 28% to 30%.
Consequently, the highest marginal individual income tax rate of 30% will apply to chargeable income exceeding RM1 million, instead of the previous RM2 million threshold.
This adjustment may increase the overall tax liability of affected high-income taxpayers.
Individuals within these income brackets should assess the potential implications and review their tax planning arrangements accordingly.
3. Understanding Malaysia’s Progressive Income Tax System
Malaysia applies a Progressive Tax System, under which different portions of an individual’s chargeable income are taxed at different rates.
This means that a taxpayer’s entire income is not automatically taxed at the highest applicable marginal rate.
For example, an individual with RM100,000 in chargeable income under the proposed YA 2027 rates would be taxed at 18% only on the portion between RM70,001 and RM100,000. The preceding income brackets would continue to be taxed at their respective rates.
It is therefore important to distinguish between Gross Income, Chargeable Income, and Marginal Tax Rate when calculating personal income tax obligations.
4. What Should Individual Taxpayers Consider?
With the proposed YA 2027 personal income tax adjustments, individuals are encouraged to review their tax positions and prepare accordingly.
Key considerations include:
- Determining their Malaysian tax residency status and applicable income tax rates.
- Identifying the relevant chargeable income brackets.
- Reviewing available personal tax reliefs and deductions.
- Maintaining proper income records and supporting documentation.
- Planning their tax affairs in accordance with current legislation.
In addition, Malaysia Budget 2027 proposes increasing the basic individual tax relief from RM9,000 to RM12,000, providing further potential tax savings for eligible individuals.
 (201706002678 & AF 002133)