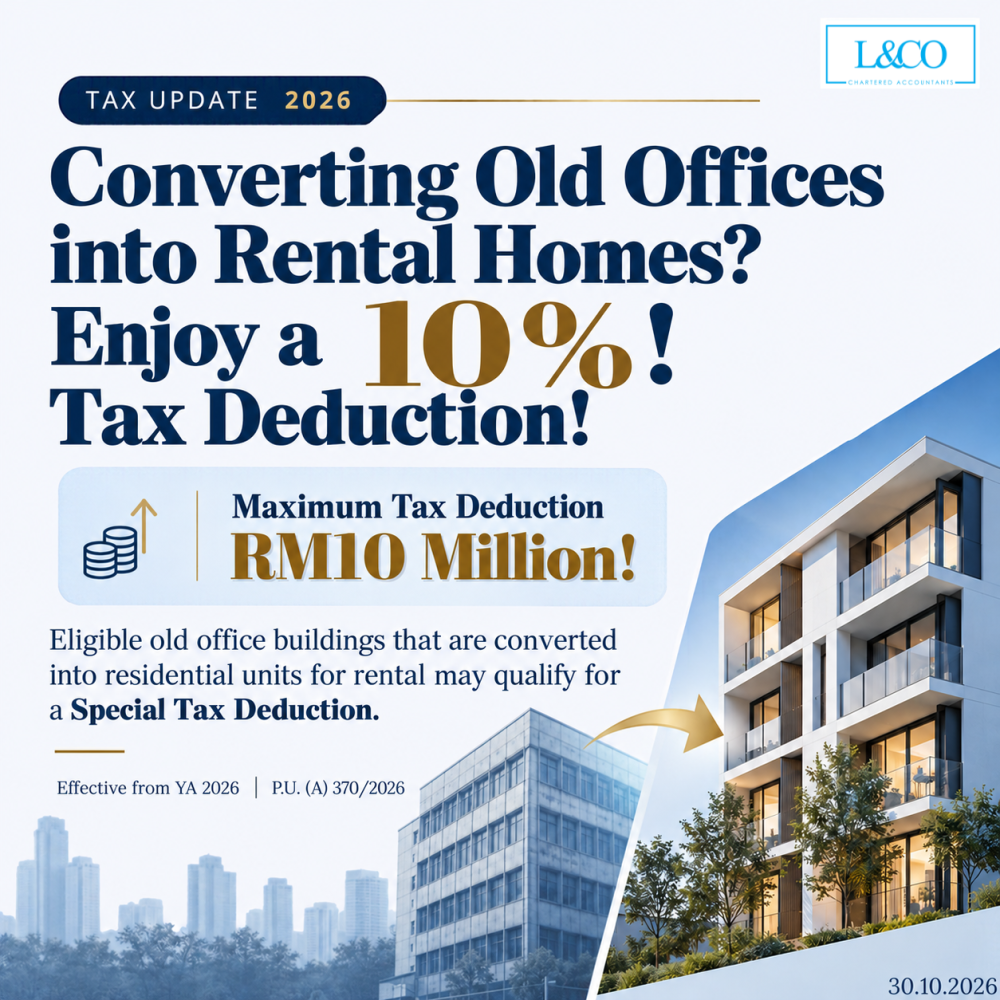
The Malaysian Government gazetted P.U. (A) 370/2026 on 27 October 2026, introducing a special tax deduction for the renovation and conversion of eligible office premises into residential properties for rental.
Under the new rules, qualifying Malaysian tax residents may claim a special tax deduction equivalent to 10% of eligible renovation and conversion expenses, capped at RM10 million, effective from the Year of Assessment (YA) 2026.
Eligibility Requirements
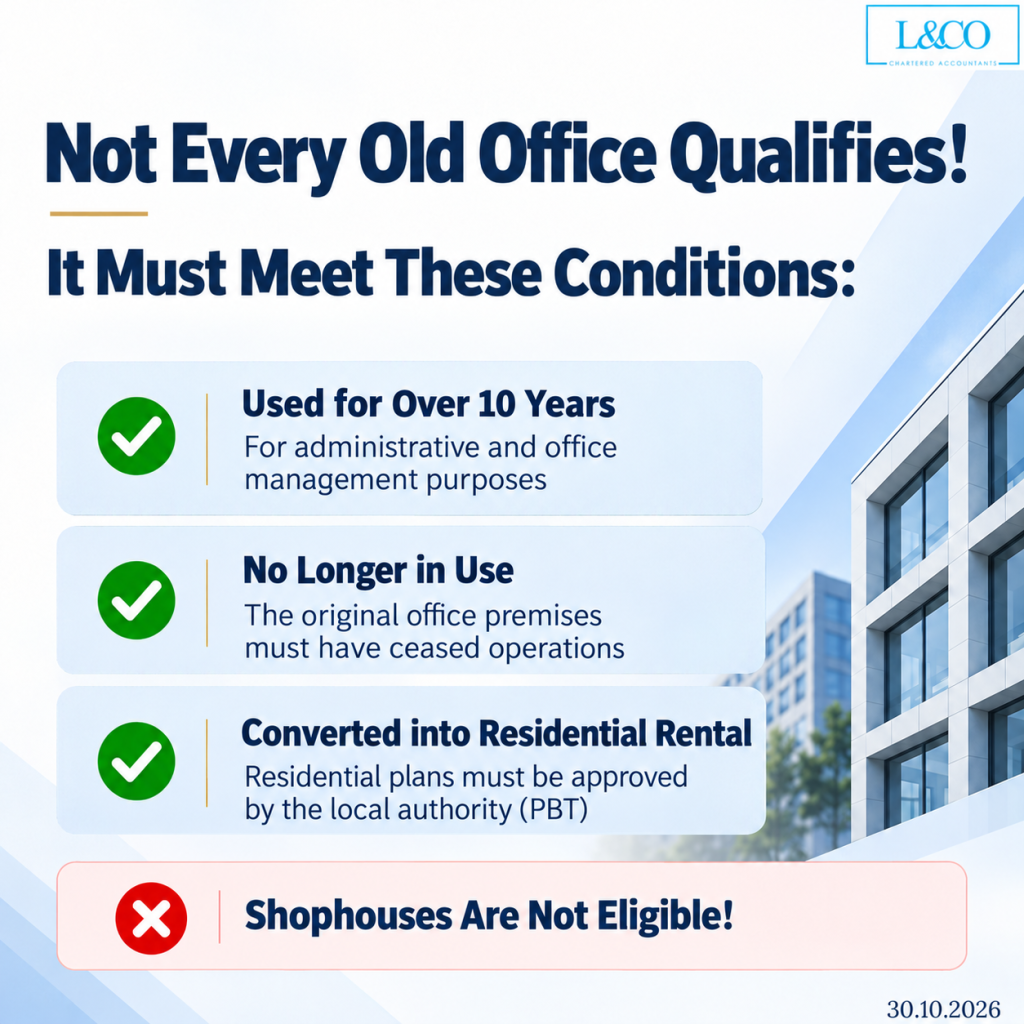
To qualify for the tax deduction, the office premises must meet the following requirements:
- Over 10 years of use: Previously used for administrative and office management purposes for more than 10 years.
- No longer in use: The original office premises must have ceased operations.
- Residential conversion: The property must be converted into residential premises for rental, with the necessary approval from the relevant Local Authority (PBT).
- Shophouses excluded: Shophouses are not eligible for this incentive.
Qualifying Renovation Expenses
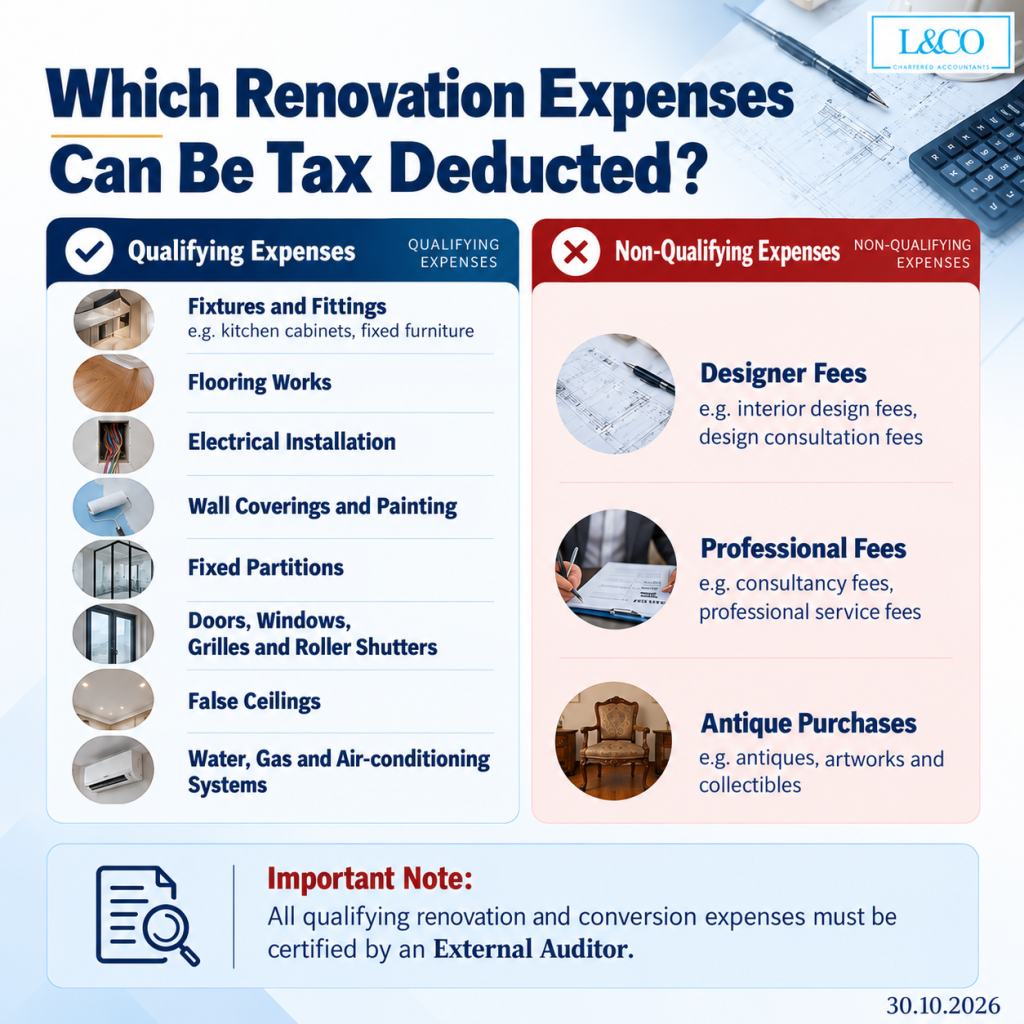
Eligible expenses include:
- Fixtures and fittings
- Flooring and electrical installations
- Wall coverings, painting and fixed partitions
- Doors, windows, grilles and roller shutters
- False ceilings
- Water, gas and air-conditioning systems
Non-qualifying expenses include designer fees, professional fees and antique purchases.
All eligible renovation and conversion expenses must be certified by an external auditor.
How Is the Tax Deduction Calculated?
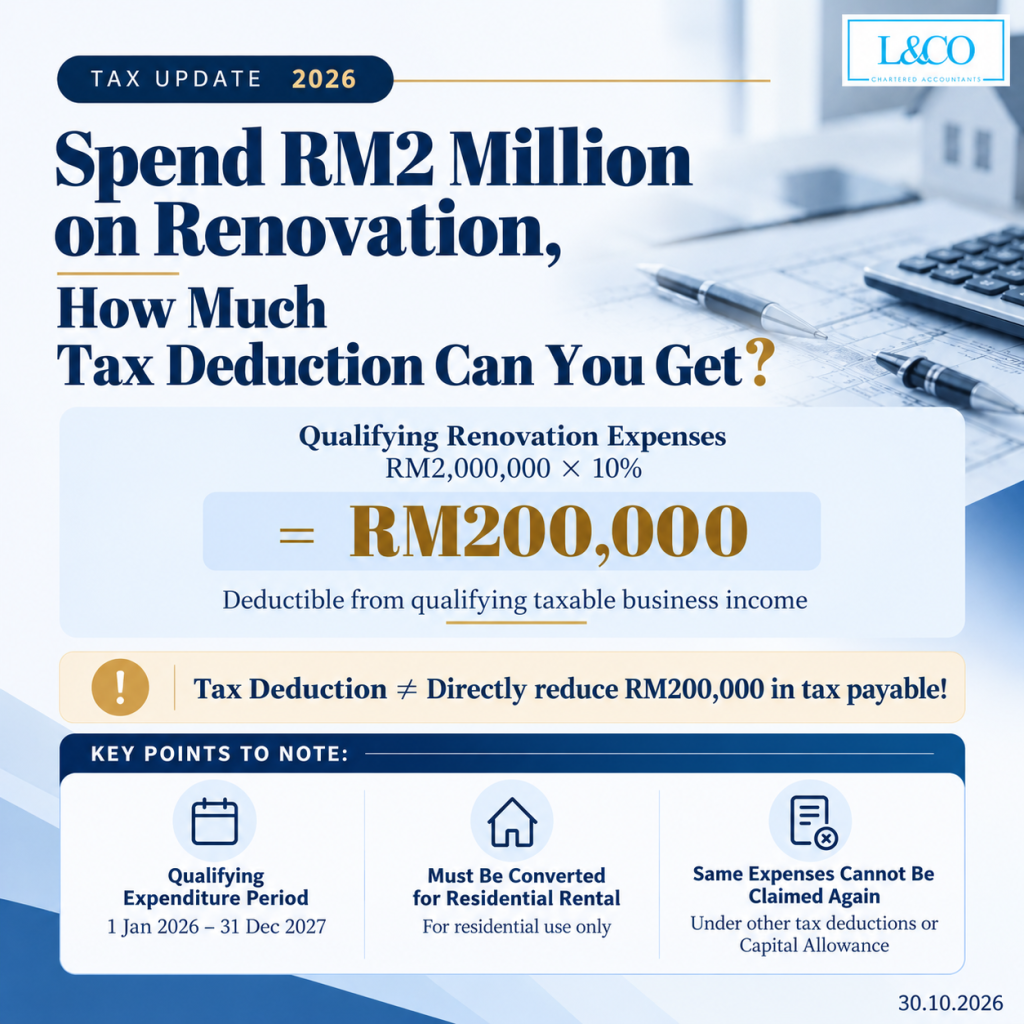
For example, a business incurs RM2,000,000 in qualifying renovation and conversion expenses:
RM2,000,000 × 10% = RM200,000
The business may claim a tax deduction of RM200,000 against its qualifying taxable business income.
It is important to note that a tax deduction does not directly reduce tax payable by the same amount. The actual tax savings depend on the applicable tax rate and the taxpayer’s circumstances.
Qualifying Period and Key Conditions
Eligible renovation and conversion expenses must be incurred between 1 January 2026 and 31 December 2027.
The qualifying converted residential premises must be used for residential rental purposes.
Furthermore, expenses already claimed under other tax deductions or capital allowances cannot be claimed again under this special incentive.