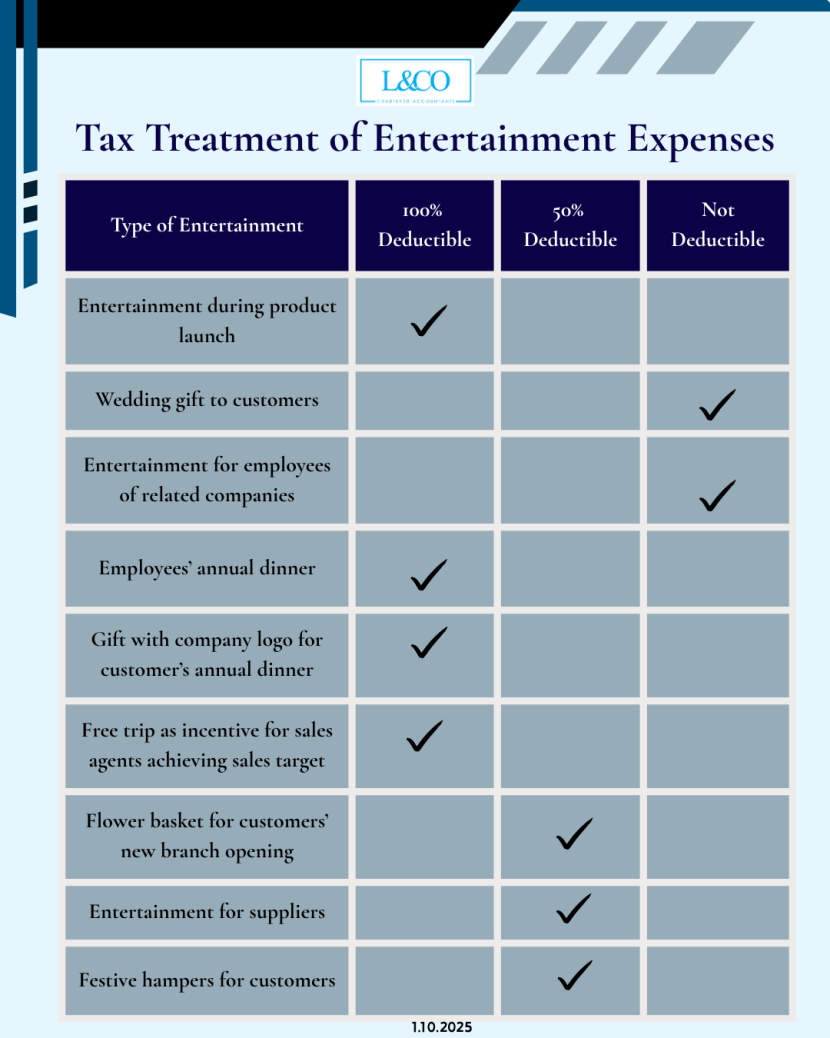
According to Income Tax Act 1967, Section 39(1)(l) and LHDN Public Ruling No. 3/2008 & 4/2015: Not all entertainment expenses are deductible. -In general, entertainment [...]
When importing goods into Malaysia, having the required documents prepared is the key to smooth customs clearance. Depending on the type of goods, different certificates [...]
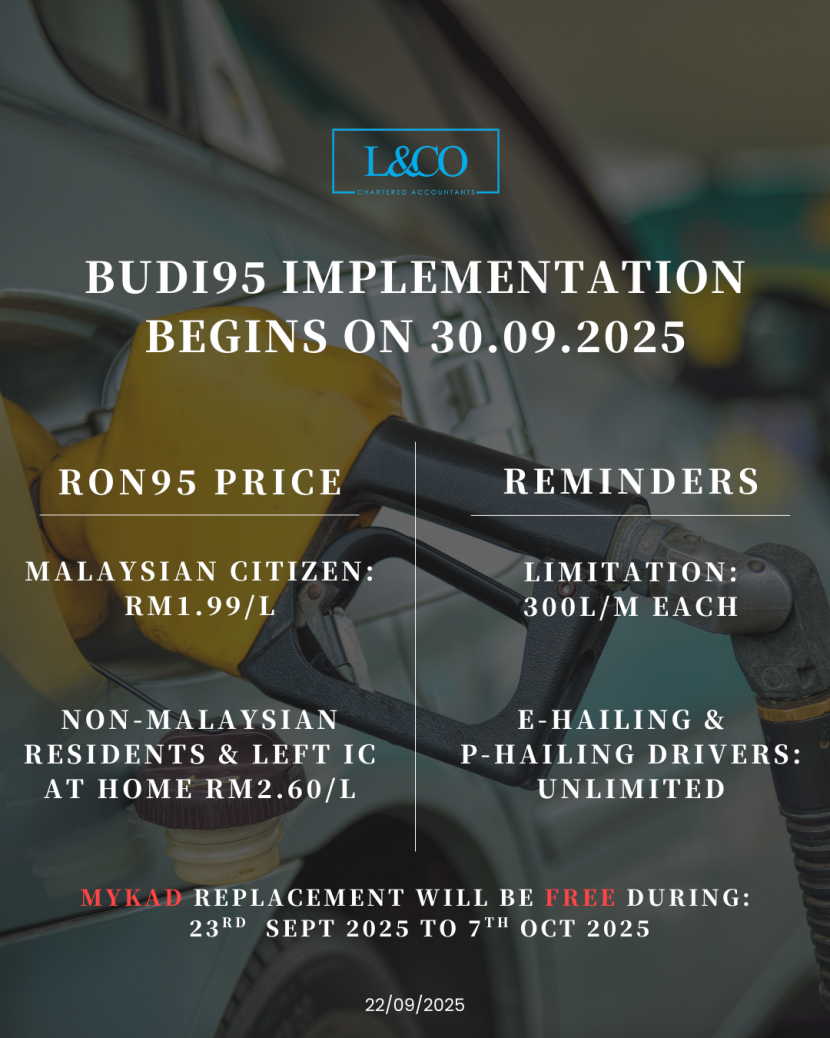
With the implementation of the new BUDI95 policy, the government is providing targeted subsidies for RON95 petrol, allowing eligible citizens to purchase it at RM1.99 [...]
Starting today, members of the public can check online to see if they qualify for the RM1.99 RON95 petrol subsidy. 👉 Check here: https://www.budi95.gov.my/ We [...]
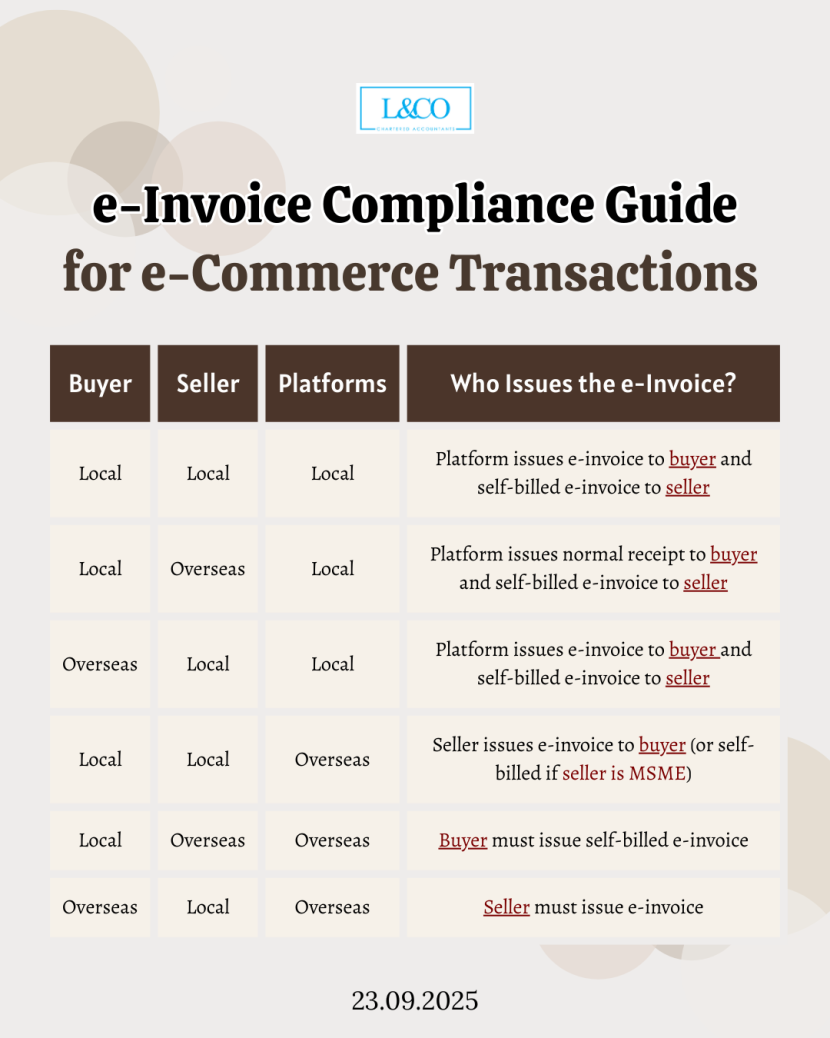
Different transaction scenarios require different invoicing approaches: Local e-commerce platforms: Must issue e-Invoices to buyers and self-billed invoices to sellers. Overseas e-commerce platforms: Not required [...]
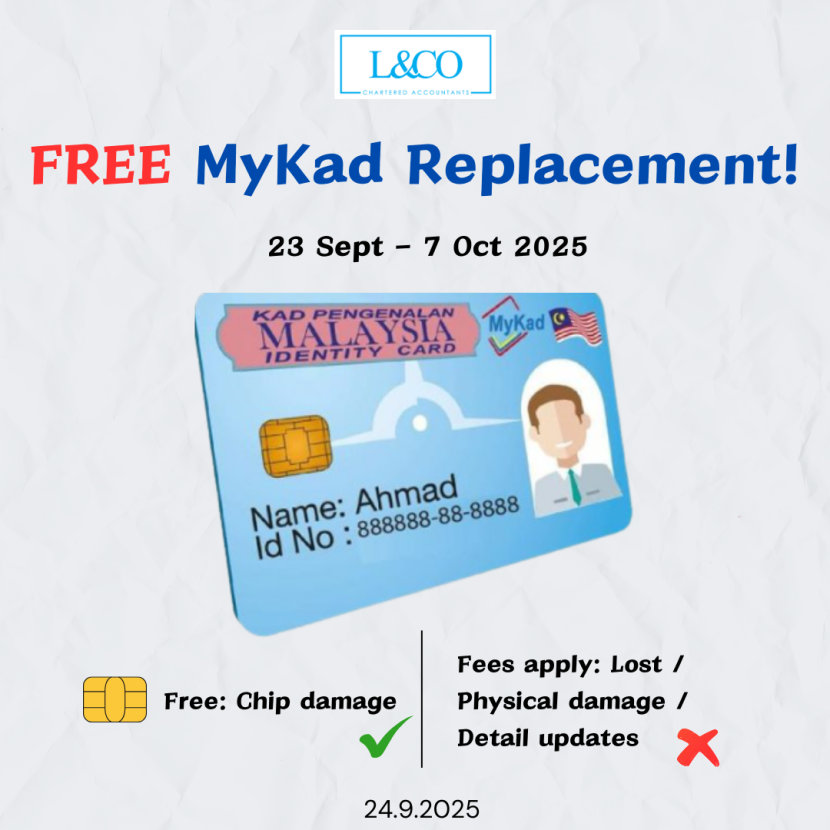
Free MyKad Replacement for Chip Damage from 23 Sept 2025 to 7 Oct 2025 The National Registration Department (NRD) has announced that from 23 September [...]
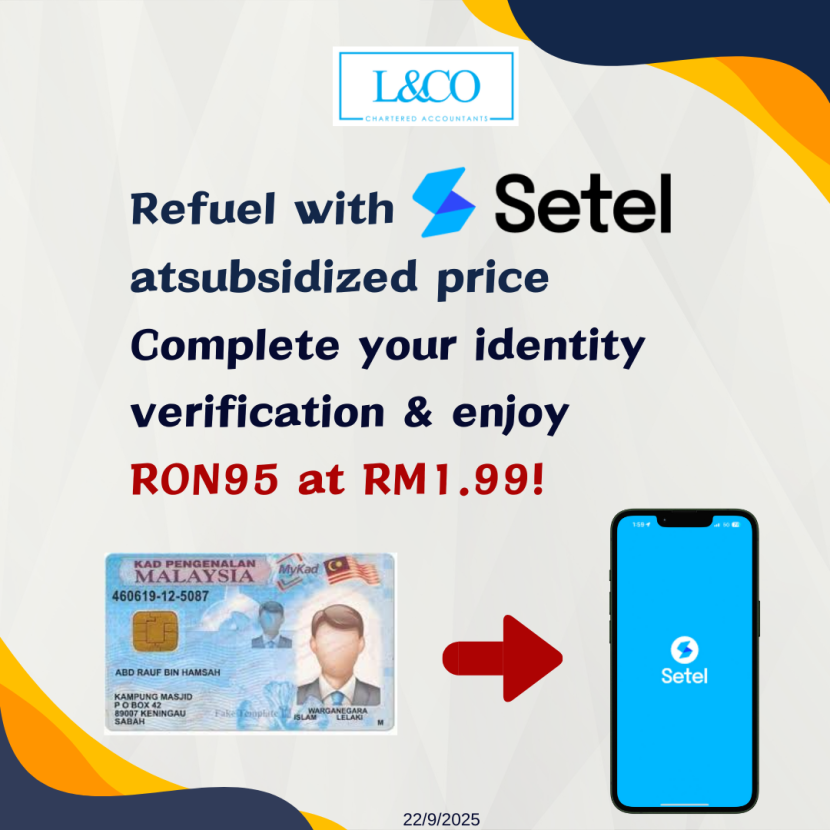
Starting from September 30, eligible vehicle owners can enjoy RON95 fuel at RM1.99 per litre. To ensure a smooth process, complete your e-KYC verification early [...]
Starting on 30th September 2025, approximately 16 million Malaysian citizens will be eligible to purchase RON95 fuel at the subsidized price of RM1.99 per litre. [...]
Contact Us
We would greatly welcome for any inquiries or favorable feedback from you.
You may submit in your inquiries via our web form below, or alternatively, you may either email us at liew@liew.my.